Audit Your Own Rental Income Before the Lender Does: A Pre-Offer Checklist
The financing condition window is open, and the lender wants your rental deposits, leases and tax returns to line up. You thought those days would go to inspection results and final numbers. Instead, you're explaining why one tenant paid two months in a single transfer and why your rental statement shows less than your bank account. You can find almost all of those questions before you make an offer, while there's no deadline attached.
If you've ever collected rent reliably every month but struggled to match the deposits to your leases and tax records, you know how fast confidence turns into worry once financing depends on explaining the differences. The rent is real. The paperwork just doesn't explain it on its own. Rent you collect only supports your next mortgage once it's backed by documents and accepted under that particular lender's rules. Checking that yourself, in advance, protects both your timeline and your purchase budget.
Four checks that show whether your rental records tell the same story
Confirm the document list first. Ask your broker what the proposed lender needs for each property you own: how many years of tax returns, how many months of bank statements, which leases. People skip this because they assume two years is the standard everywhere. Requirements vary by lender and by file, and guessing wrong means a second round of requests mid-condition.
Collect your filed tax evidence. Gather the T1 income tax returns, T776 Statements of Real Estate Rentals and CRA Notices of Assessment the lender asks for. Each document does a different job. The Notice of Assessment confirms CRA processed your return. The T776 shows income and expenses property by property. People leave this with their accountant until asked, and an unfiled or unassessed return is one of the easiest ways to stall a file.
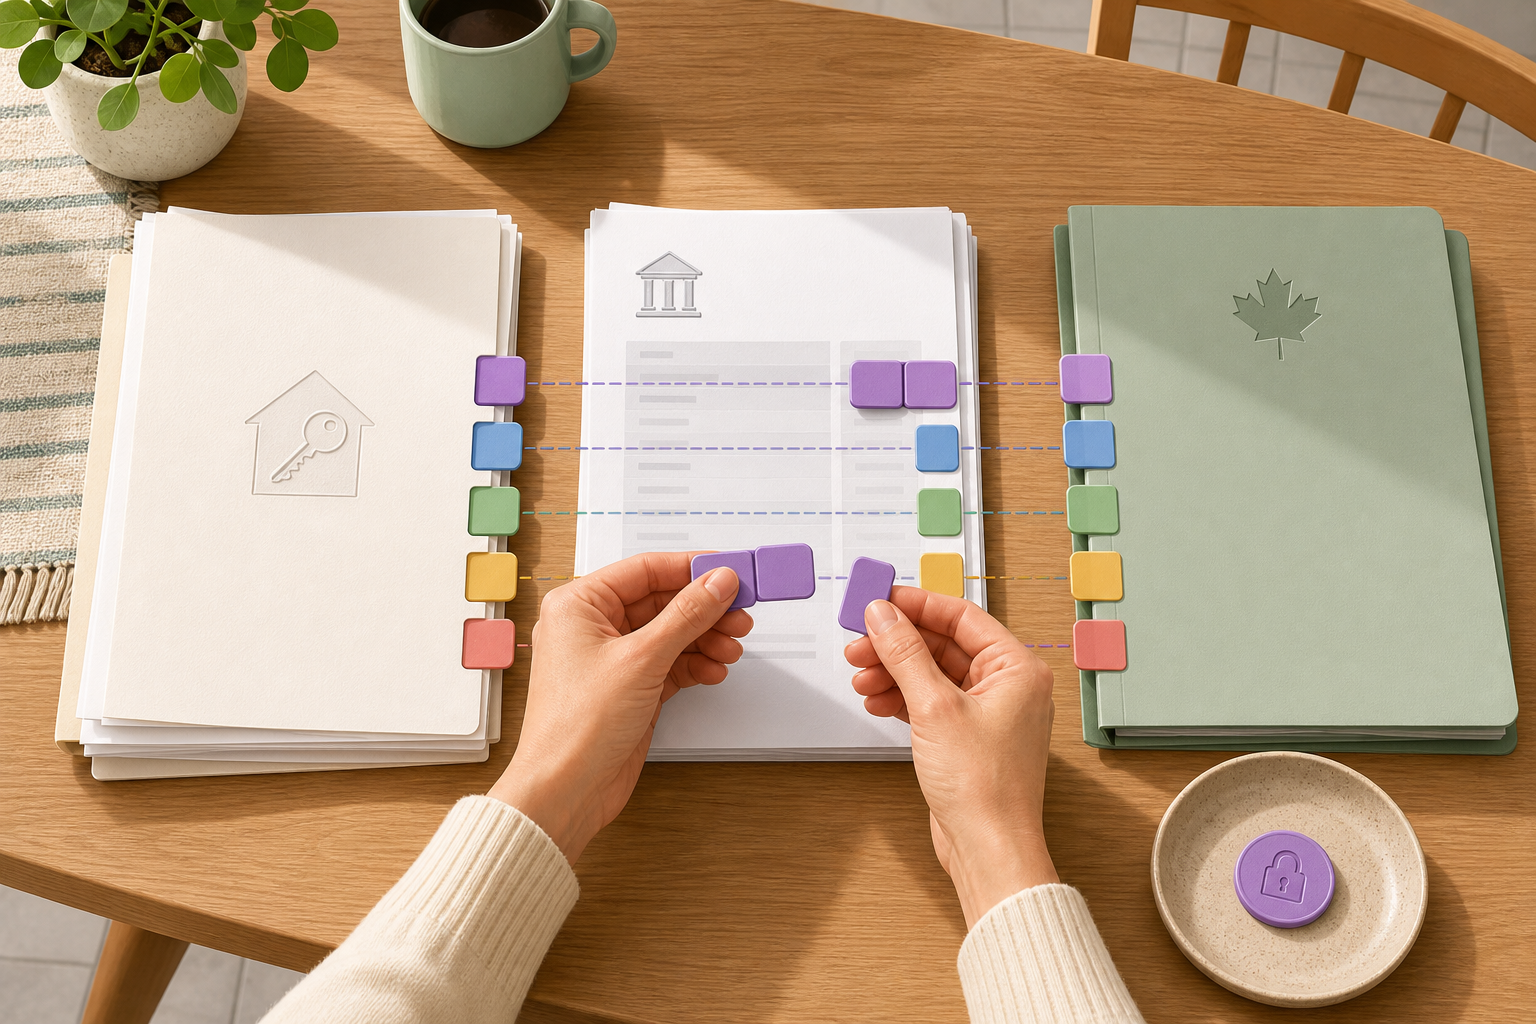
Match each lease to the money that arrived. Put your current signed tenancy agreements, including any rent increases, beside your bank deposits. Mark security deposits separately from rent. Note any gaps, and explain combined payments such as two months in one e-transfer or rent bundled with utilities. This gets skipped because the rent always shows up. A lender, though, only sees what your records show. If a property manager handles the unit, their year-end statement does much of this work for you.
Explain the differences instead of forcing totals to match. Your annual gross rent, the net rental income on your T776 and your bank deposits can legitimately differ because of expenses, timing or a month of vacancy. Write a short note for each difference and keep the receipts that support it. If something looks like a filing mistake, take it to your accountant now. Keep in mind that heavy write-offs lower the net figure some lenders work from, so a great tax year can mean a smaller qualifying number.
How to find out how much of your rent the lender will actually count
Check what rent will actually qualify. CMHC describes lenders crediting somewhere between 50% and 80% of gross rent toward qualifying, and the method differs from lender to lender. As an illustration, on $2,000 of monthly rent, a 50% credit counts $1,000 and an 80% credit counts $1,600. That $600 a month changes how much you can borrow, which is why dependable cash flow doesn't automatically produce the borrowing amount you expected.
Ask your broker to run the proposed lender's calculation and list any missing evidence before you settle on a purchase price. If the property you're buying will be a rental with no tax history yet, ask whether the lender will want an appraisal with a market rent assessment. Treat this review as a way to surface questions early. The property itself still has to be approved once you've made an offer.
Collecting rent shows your tenants are reliable. Proving qualifying income shows the lender what that rent is worth on paper, and that's the part you can prepare. Pick one rental this week. Set its lease, its last few months of deposits and its latest filed rental statement side by side, and see whether they tell the same story.

The financing condition window is open, and the lender wants your rental deposits, leases and tax returns to line up. You thought those days would go to inspection results and final numbers. Instead, you're explaining why one tenant paid two months in a single transfer and why your rental statement shows less than your bank account. You can find almost all of those questions before you make an offer, while there's no deadline attached.
If you've ever collected rent reliably every month but struggled to match the deposits to your leases and tax records, you know how fast confidence turns into worry once financing depends on explaining the differences. The rent is real. The paperwork just doesn't explain it on its own. Rent you collect only supports your next mortgage once it's backed by documents and accepted under that particular lender's rules. Checking that yourself, in advance, protects both your timeline and your purchase budget.
Four checks that show whether your rental records tell the same story
Confirm the document list first. Ask your broker what the proposed lender needs for each property you own: how many years of tax returns, how many months of bank statements, which leases. People skip this because they assume two years is the standard everywhere. Requirements vary by lender and by file, and guessing wrong means a second round of requests mid-condition.
Collect your filed tax evidence. Gather the T1 income tax returns, T776 Statements of Real Estate Rentals and CRA Notices of Assessment the lender asks for. Each document does a different job. The Notice of Assessment confirms CRA processed your return. The T776 shows income and expenses property by property. People leave this with their accountant until asked, and an unfiled or unassessed return is one of the easiest ways to stall a file.
Match each lease to the money that arrived. Put your current signed tenancy agreements, including any rent increases, beside your bank deposits. Mark security deposits separately from rent. Note any gaps, and explain combined payments such as two months in one e-transfer or rent bundled with utilities. This gets skipped because the rent always shows up. A lender, though, only sees what your records show. If a property manager handles the unit, their year-end statement does much of this work for you.
Explain the differences instead of forcing totals to match. Your annual gross rent, the net rental income on your T776 and your bank deposits can legitimately differ because of expenses, timing or a month of vacancy. Write a short note for each difference and keep the receipts that support it. If something looks like a filing mistake, take it to your accountant now. Keep in mind that heavy write-offs lower the net figure some lenders work from, so a great tax year can mean a smaller qualifying number.
How to find out how much of your rent the lender will actually count
Check what rent will actually qualify. CMHC describes lenders crediting somewhere between 50% and 80% of gross rent toward qualifying, and the method differs from lender to lender. As an illustration, on $2,000 of monthly rent, a 50% credit counts $1,000 and an 80% credit counts $1,600. That $600 a month changes how much you can borrow, which is why dependable cash flow doesn't automatically produce the borrowing amount you expected.
Ask your broker to run the proposed lender's calculation and list any missing evidence before you settle on a purchase price. If the property you're buying will be a rental with no tax history yet, ask whether the lender will want an appraisal with a market rent assessment. Treat this review as a way to surface questions early. The property itself still has to be approved once you've made an offer.
Collecting rent shows your tenants are reliable. Proving qualifying income shows the lender what that rent is worth on paper, and that's the part you can prepare. Pick one rental this week. Set its lease, its last few months of deposits and its latest filed rental statement side by side, and see whether they tell the same story.
Read Next
When Prime Rises, the Biggest Smith Manoeuvre™ Risk Is Your Own Reaction
The Bank of Canada Targets 2%, and Your Mortgage Plan Should Too
The CRA Ignores Your Collateral and Asks One Question: What Did You Buy?
5% Down or 20% Down: What the Smaller Deposit Costs Over 25 Years