Your Renewal Switch Skips the Stress Test, Until You Borrow More
A renewal letter arrives with a rate a little higher than the ones advertised down the street, and the homeowner holding it hesitates. Switching lenders used to mean qualifying all over again at a tougher rate. Plenty of people with spotless payment histories signed their bank's offer because they weren't sure they'd pass anywhere else. That hesitation has a price: weaker footing when you negotiate, and sometimes a higher payment for the next five years.
If you've ever opened a renewal offer and wondered whether you could get a better payment while also borrowing for a renovation, you know how fast a simple decision turns into a guessing game. The rules have loosened, but only for one kind of move. Knowing which kind you're asking for decides whether the stress test applies, and it keeps you from spending your renewal window on options that can't give you what you need.
You can shop your renewal without automatically facing another stress test
Since November 21, 2024, OSFI no longer requires federally regulated lenders, such as the big banks, to stress test an uninsured mortgage that moves over in a straight switch at renewal. Uninsured means the mortgage doesn't carry mortgage default insurance, the coverage a lender requires when a buyer puts down less than 20%. A straight switch means the new lender takes over the same balance with the same remaining amortization. If you have 17 years left, you move with 17 years left. Insured mortgages already had this treatment for straight switches.
The change was meant to open up competition. A borrower whose income or debts wouldn't clear the stress test today can still let a second lender bid on the mortgage they already carry. A competing offer is the strongest thing you can bring to your current bank, whether you end up moving or not.
Removing the federal requirement doesn't hand you an approval. The receiving lender still pulls your credit, confirms your income and checks the value of your home. If that value has slipped, it can change what the lender will offer. BC credit unions answer to provincial regulators, so ask any credit union directly what it requires for a switch. Some follow the federal approach, and some set their own criteria.
Why borrowing more at renewal brings the stress test back
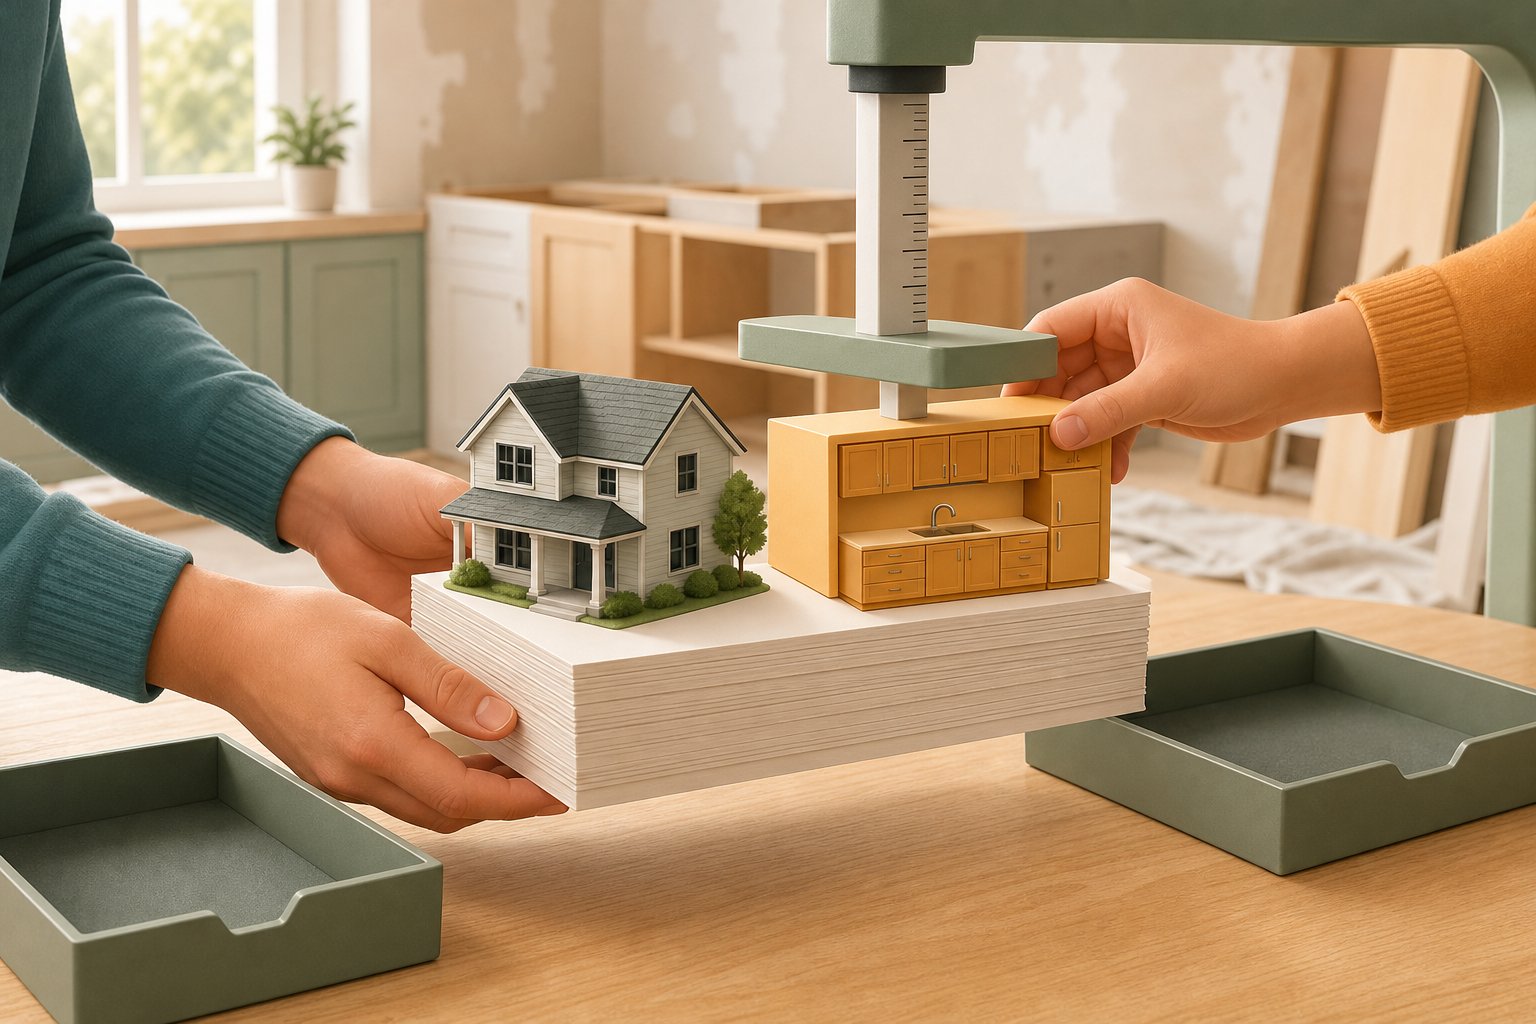
Now change the request. Say you want an extra $40,000 for a kitchen, or you want to fold a car loan and a credit card into the mortgage. Maybe you want to stretch those 17 years back to 25 to lower the payment, or add a home equity line of credit. Each one asks the lender to approve borrowing it hasn't approved before. Even a small top-up takes you outside the straight switch exemption. A federally regulated lender will generally qualify you at the stress test rate: the higher of your contract rate plus two percentage points, or 5.25%. On an illustrative 4.5% offer, that means showing you can carry payments at 6.5%.
Before you compare offers, get clear answers to a few questions:
Does this move qualify as an uninsured straight switch, with my balance and remaining amortization unchanged?
Am I adding anything: cash out, consolidated debt, a longer amortization or a new line of credit?
What does the new lender still check, even without the stress test?
What will it cost to move? Legal, appraisal, discharge and transfer fees can wipe out a small rate difference. "No-fee" switches often carry a slightly higher rate to cover those costs.
Permission to move your existing mortgage is not permission to borrow more. Easier switching widens the list of lenders who can compete for the loan you already have. How much any of them will lend you is a separate approval.
Equity alone doesn't approve new debt, but your renewal can still be the moment you choose your lender. Before you collect a single offer, tell your broker or lender which request you're making: move the mortgage exactly as it is, or borrow more. Every quote that follows depends on that answer.

A renewal letter arrives with a rate a little higher than the ones advertised down the street, and the homeowner holding it hesitates. Switching lenders used to mean qualifying all over again at a tougher rate. Plenty of people with spotless payment histories signed their bank's offer because they weren't sure they'd pass anywhere else. That hesitation has a price: weaker footing when you negotiate, and sometimes a higher payment for the next five years.
If you've ever opened a renewal offer and wondered whether you could get a better payment while also borrowing for a renovation, you know how fast a simple decision turns into a guessing game. The rules have loosened, but only for one kind of move. Knowing which kind you're asking for decides whether the stress test applies, and it keeps you from spending your renewal window on options that can't give you what you need.
You can shop your renewal without automatically facing another stress test
Since November 21, 2024, OSFI no longer requires federally regulated lenders, such as the big banks, to stress test an uninsured mortgage that moves over in a straight switch at renewal. Uninsured means the mortgage doesn't carry mortgage default insurance, the coverage a lender requires when a buyer puts down less than 20%. A straight switch means the new lender takes over the same balance with the same remaining amortization. If you have 17 years left, you move with 17 years left. Insured mortgages already had this treatment for straight switches.
The change was meant to open up competition. A borrower whose income or debts wouldn't clear the stress test today can still let a second lender bid on the mortgage they already carry. A competing offer is the strongest thing you can bring to your current bank, whether you end up moving or not.
Removing the federal requirement doesn't hand you an approval. The receiving lender still pulls your credit, confirms your income and checks the value of your home. If that value has slipped, it can change what the lender will offer. BC credit unions answer to provincial regulators, so ask any credit union directly what it requires for a switch. Some follow the federal approach, and some set their own criteria.
Why borrowing more at renewal brings the stress test back
Now change the request. Say you want an extra $40,000 for a kitchen, or you want to fold a car loan and a credit card into the mortgage. Maybe you want to stretch those 17 years back to 25 to lower the payment, or add a home equity line of credit. Each one asks the lender to approve borrowing it hasn't approved before. Even a small top-up takes you outside the straight switch exemption. A federally regulated lender will generally qualify you at the stress test rate: the higher of your contract rate plus two percentage points, or 5.25%. On an illustrative 4.5% offer, that means showing you can carry payments at 6.5%.
Before you compare offers, get clear answers to a few questions:
Permission to move your existing mortgage is not permission to borrow more. Easier switching widens the list of lenders who can compete for the loan you already have. How much any of them will lend you is a separate approval.
Equity alone doesn't approve new debt, but your renewal can still be the moment you choose your lender. Before you collect a single offer, tell your broker or lender which request you're making: move the mortgage exactly as it is, or borrow more. Every quote that follows depends on that answer.
Read Next
Audit Your Own Rental Income Before the Lender Does: A Pre-Offer Checklist
When Prime Rises, the Biggest Smith Manoeuvre™ Risk Is Your Own Reaction
The Bank of Canada Targets 2%, and Your Mortgage Plan Should Too
The CRA Ignores Your Collateral and Asks One Question: What Did You Buy?